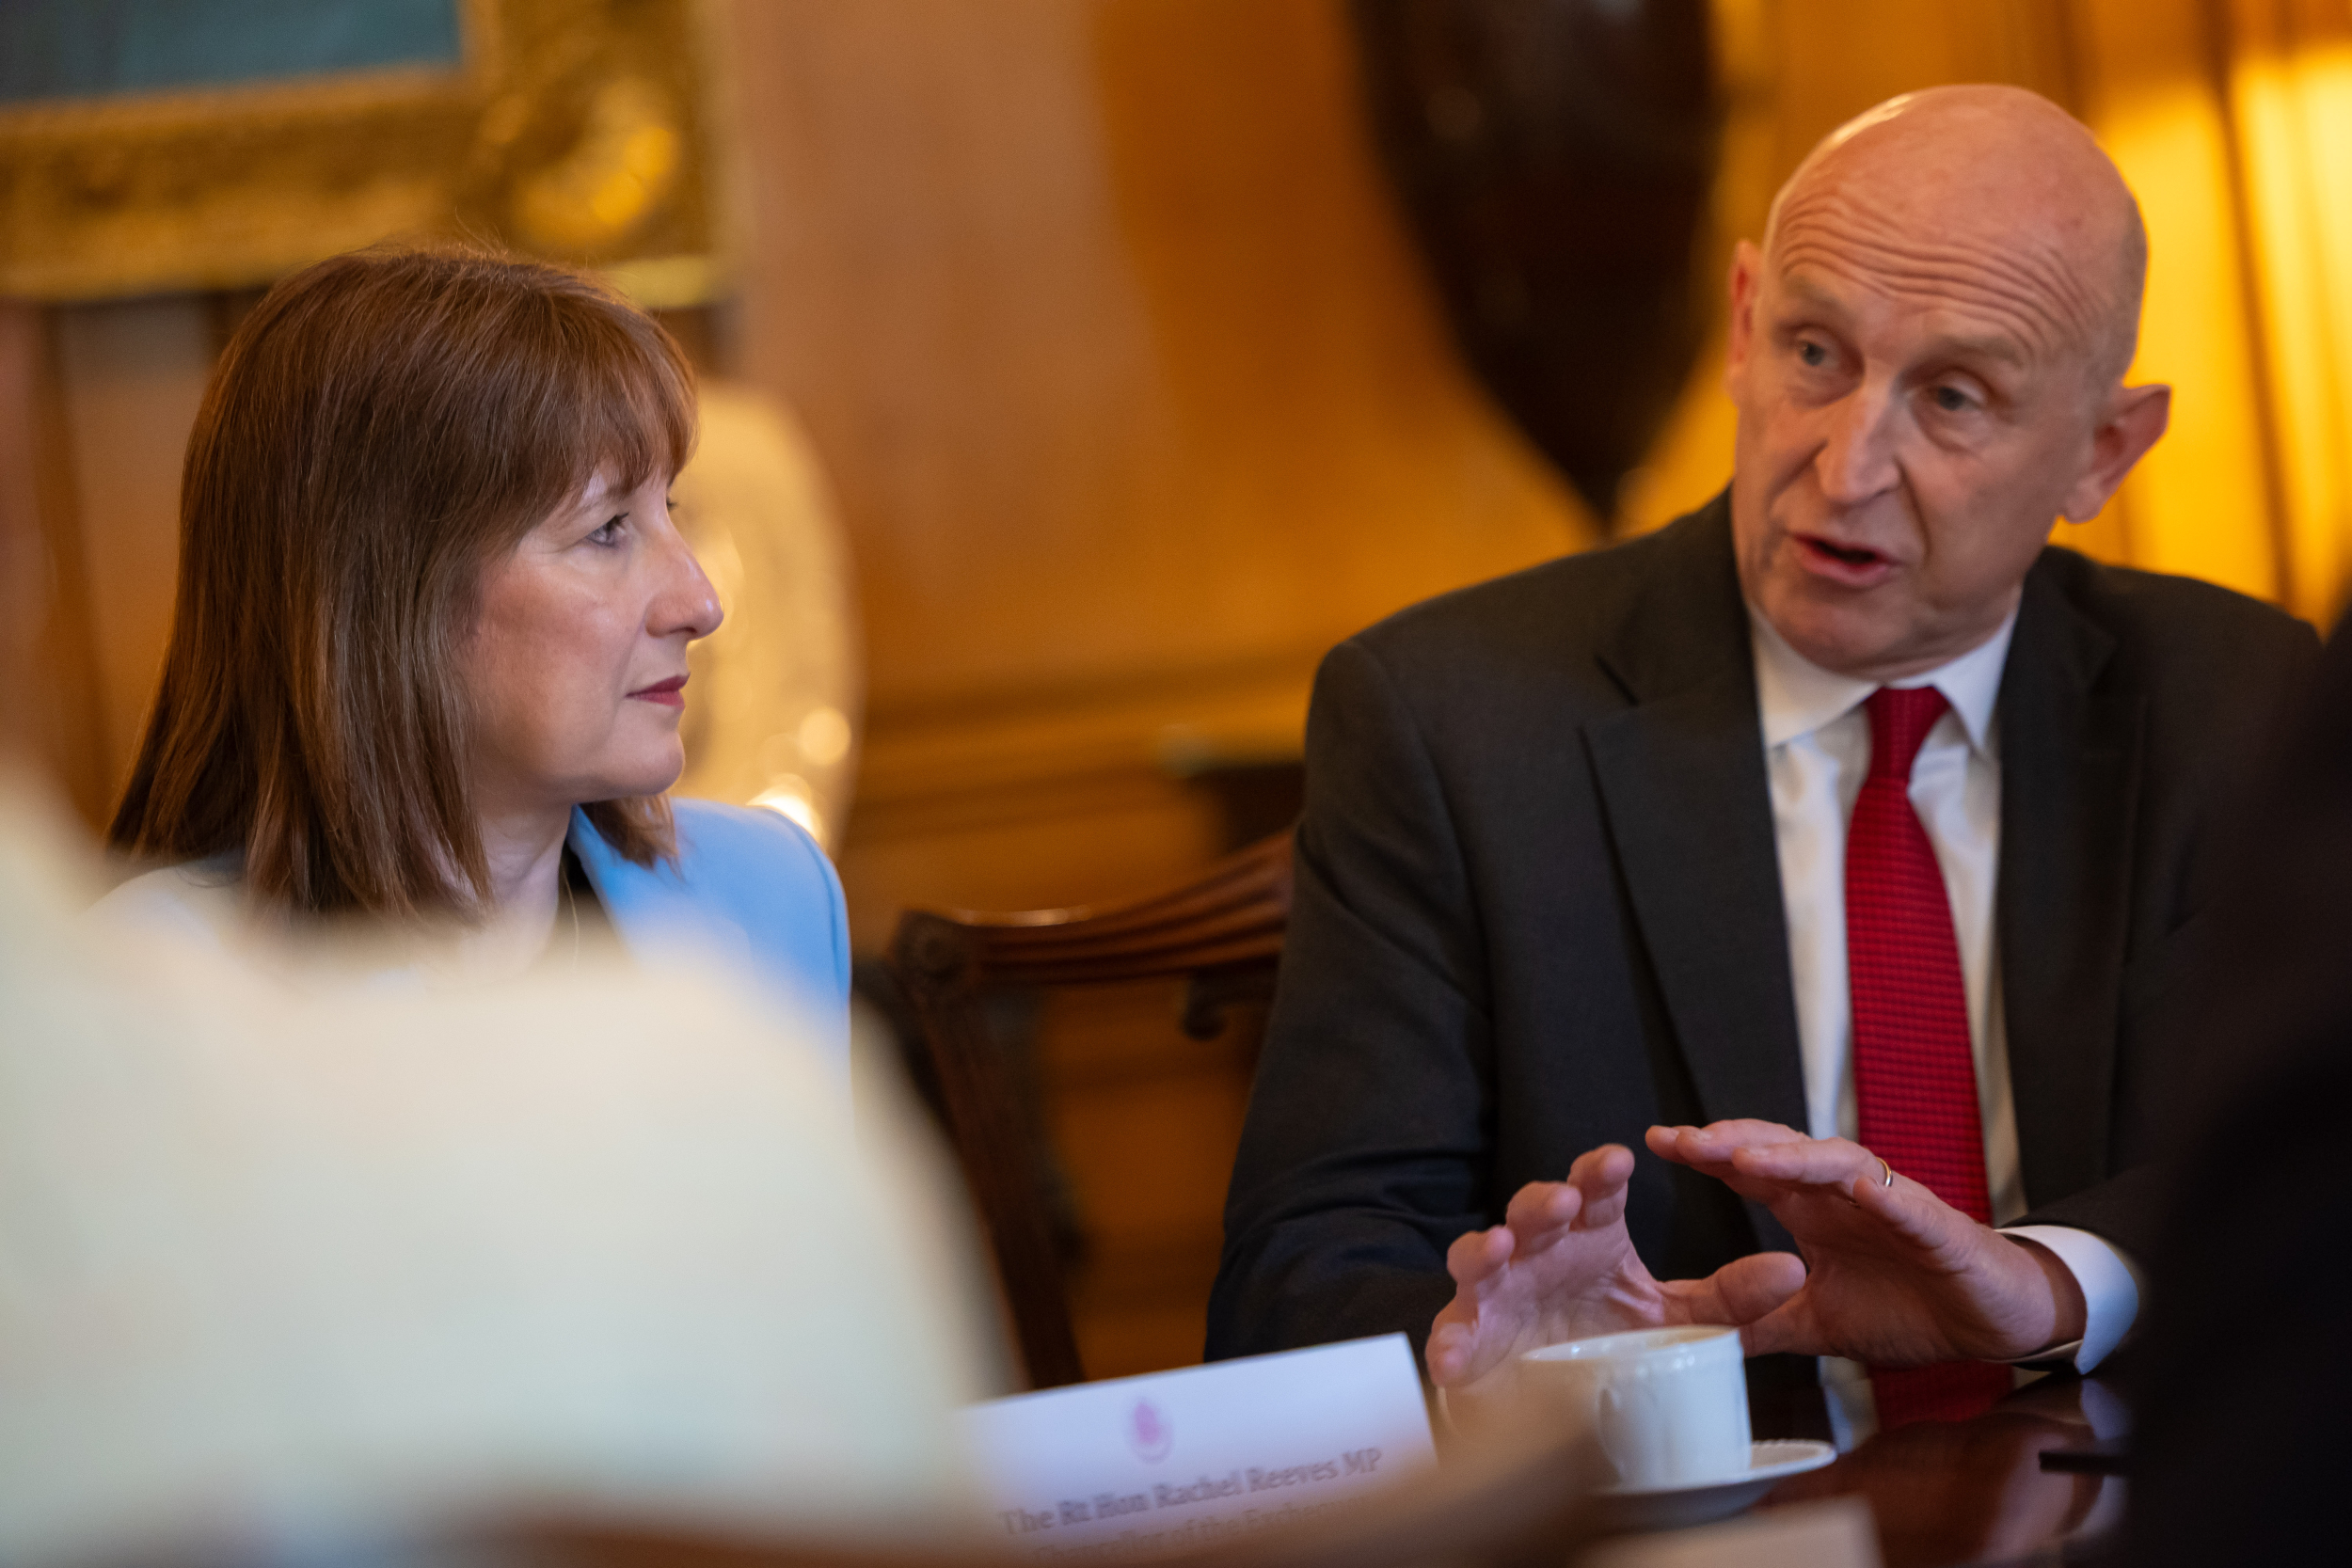
As the United Kingdom approaches the Autumn Budget, the political atmosphere is thick with anticipation regarding the future of retirement income. Chancellor John Healey is preparing to unveil a significant policy shift designed to insulate low-income retirees from the creeping burden of income tax. At the heart of this proposal is a custom tax shield, set at £13,036, intended to prevent the state pension from dragging millions of elderly citizens into the tax net. The problem, however, lies in the friction between this new threshold and the existing, frozen personal allowance of £12,570.
To understand the necessity of this intervention, one must look at the state pension itself. The government remains committed to the triple lock—a mechanism that ensures the state pension rises in line with the highest of inflation, earnings, or 2.5%. With a projected 3.9% increase on the horizon, the state pension is set to climb to £13,036. While this provides a vital cost-of-living boost for many, it creates a structural collision: the payment will soon exceed the personal allowance, meaning that for the first time, the state pension alone will push recipients into the taxable bracket.
Healey’s proposed solution is to create a bespoke allowance for retirees, effectively shielding that £13,036 from the taxman. On the surface, this is a protective measure. Yet, the simplicity of the plan masks a complex administrative reality. By creating a hard, arbitrary threshold rather than a graduated system, the Treasury is effectively drawing a line in the sand that separates those who receive government support from those who have managed to build even a small private nest egg.
Without a taper system to smooth the transition, retirees who possess modest secondary savings face a sharp financial penalty.
Industry experts have begun to sound the alarm, warning that the policy may inadvertently create one of the most perverse incentives in the history of British retirement planning. Because the tax shield is not tapered, it acts as a binary switch. If a retiree has a small private pension that pushes their total income just over the £13,036 mark, they may find themselves liable for taxes that negate the value of their private savings. The logical, albeit unfortunate, response for many will be to spend down their private savings as quickly as possible to ensure they remain under the threshold and qualify for the full tax break.
Former pensions minister Steve Webb has been particularly vocal about the risks, describing the situation as a growing cliff-edge problem. Without a taper system to smooth the transition, retirees who possess modest secondary savings face a sharp financial penalty. This creates a scenario where the government is effectively taxing the prudence of those who attempted to supplement their state income.
Beyond the immediate impact on retirees, the policy presents a long-term fiscal headache for the Treasury. Steve Webb has noted that the concession could become increasingly expensive and difficult for governments to withdraw once it is established. Furthermore, while the current government intends to maintain the triple lock for this parliamentary term, there is already talk of altering the mechanism starting in 2030. This creates a landscape of perpetual uncertainty for retirees, who must navigate a tax system that seems to shift beneath their feet.
As the Autumn Budget approaches, the challenge for John Healey is to balance the immediate need to protect pensioners from rising tax bills with the long-term goal of encouraging private savings. The current proposal, while well-intentioned, risks creating an administrative nightmare and a financial trap for the very people it aims to support. Whether the Treasury will introduce a more nuanced approach remains to be seen, but for now, the proposed tax shield stands as a stark reminder of how complex the intersection of social security and private finance can be.
